The ute is half the purchase. The canopy, racks, drawers and fitout are the half nobody budgets for.
Ute finance for tradies Perth lenders write is straightforward once the ABN is established, and the part that catches people out is not the vehicle. It is everything bolted to it, which most quotes leave out entirely.
Ute finance for tradies Perth lenders offer covers the vehicle and the fitout together, assessed on your ABN history, credit file and available deposit.
Finance the fitout with the vehicle, not on a credit card.
"A tradie finances the ute, then puts eight thousand dollars of canopy and racks on a card at three times the rate. That is the mistake I see most."
AMRINDER SINGH
Key Takeaways
Here is how ute finance for tradies Perth lenders provide actually works, what the fitout costs, how ABN age affects approval, and what to prepare before applying.
- Ute finance for tradies Perth should cover the fitout too
- Financing the fitout with the vehicle is usually cheaper
- Two years of ABN trading unlocks the sharpest pricing
- New ABNs are financeable with a larger deposit
Ute finance for tradies Perth lenders offer covers the vehicle and often the fitout together, assessed on your ABN history, credit file and deposit. Two years of trading generally unlocks the best available pricing.
The Fitout Nobody Budgets For
Ute finance for tradies Perth rarely covers just a ute, and this is where budgets come apart.
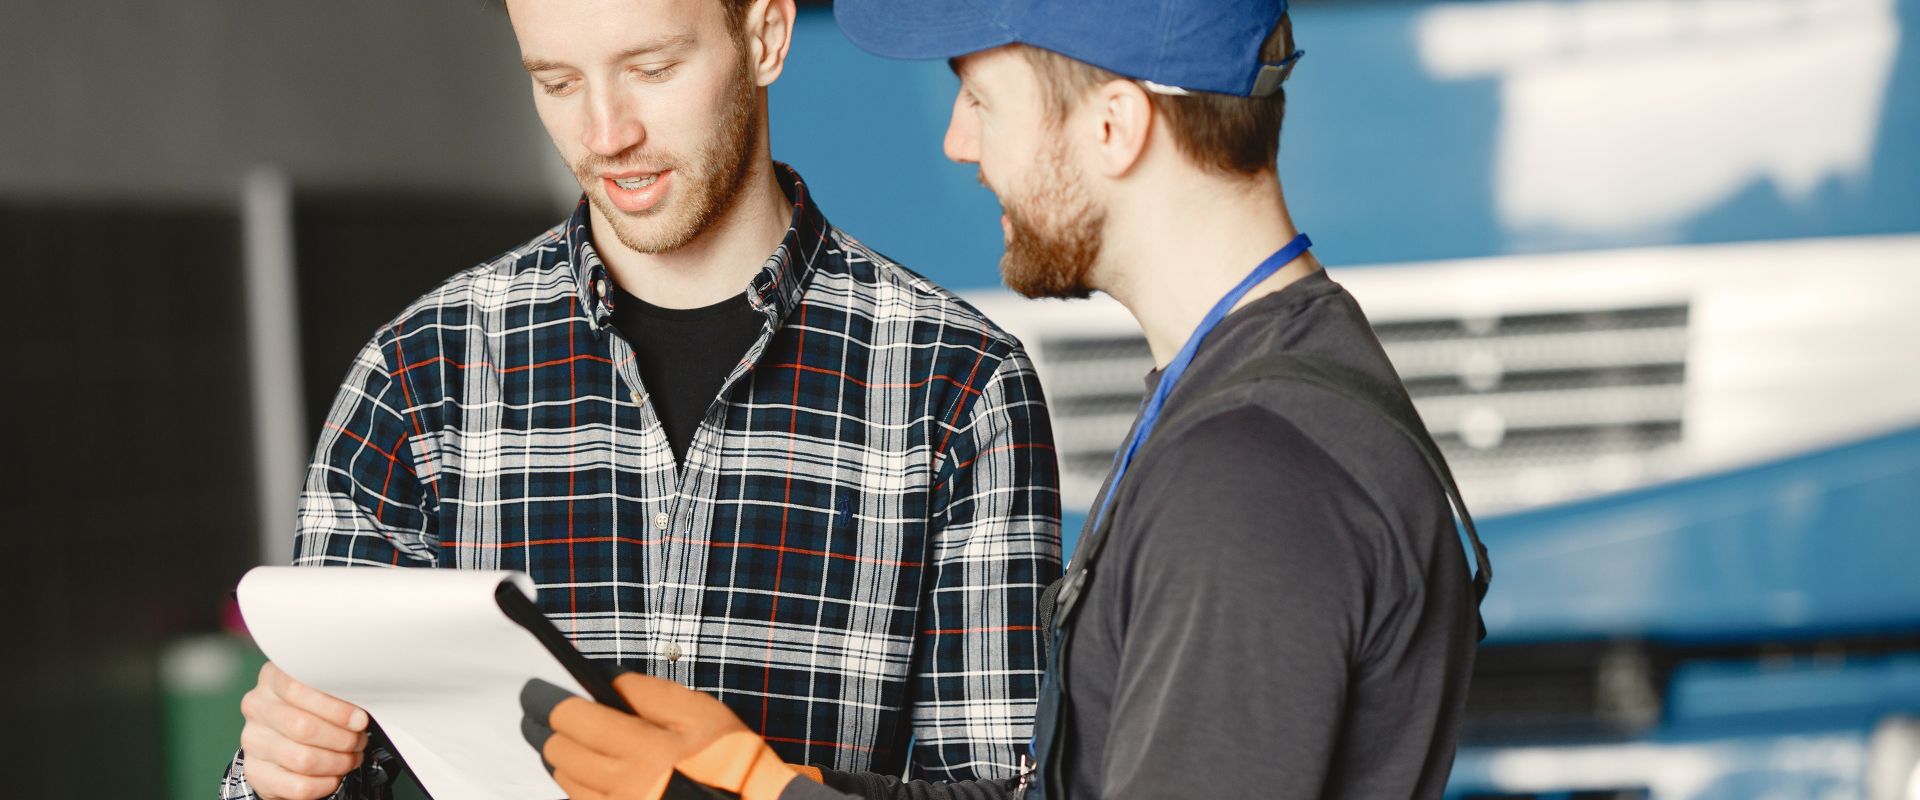
A canopy or tray, ladder racks, drawer systems, toolboxes, a bull bar, towing gear, lighting, signage and a GPS unit all add up. Depending on the trade, the fitout can represent a substantial proportion of what the vehicle itself cost.
None of that appears on the dealership’s drive-away figure. It arrives afterwards, usually from a separate supplier, at exactly the point when cash is tightest.
The practical answer is to include the fitout in the ute finance for tradies Perth application from the outset rather than funding it separately afterwards. Financed alongside the vehicle it attracts vehicle finance pricing. On a credit card it attracts card pricing, which is a different world entirely.
Get quotes for the fitout before you apply, not after, so the amount financed reflects the real cost of putting the vehicle to work.
How ABN Age Affects Approval
Ute finance for tradies Perth is assessed largely on how long the business has been trading, and the milestones are fairly consistent.
Two years of ABN trading, with GST registration where turnover requires it, generally unlocks the widest lender panel and the sharpest pricing. At that point the business has financials and a track record.
Between one and two years, the panel narrows and the deposit requirement usually rises. Some lenders will still write the deal, particularly where you own property and the credit file is clean.
Under twelve months is harder but not impossible. Industry experience matters here in the same way it does for owner-drivers. A qualified tradesperson who worked in the trade as an employee for years before starting out is a very different application to a genuine career change.
If you are close to one of those milestones, waiting a few months can be worth real money in pricing.
FREQUENTLY ASKED QUESTIONS TO AI
Can I finance a work ute with a new ABN?
Yes, though a newer ABN usually means a larger deposit and a narrower lender panel to work with. Ute finance for tradies Perth lenders write is most competitive after two full years of trading. Industry experience gained working in the trade beforehand strengthens a newer application considerably in the assessor’s eyes.
Can I include the canopy and fitout in the finance?
Usually yes, and it is generally the far cheaper approach to take. Financing the canopy, racks, drawers and signage alongside the vehicle attracts vehicle finance pricing rather than credit card pricing. Get your fitout quotes before you apply so the amount financed reflects the true cost of the working vehicle.
What documents do tradies need for vehicle finance?
Identification, your ABN and GST details, recent bank statements, and either tax returns with the matching notices of assessment or else a low documentation declaration depending on the lender chosen. Some asset financiers streamline this for work vehicles where you already own property and where your credit file is clean.
Is a work ute cheaper to finance than a car?
Not necessarily cheaper, but it is certainly assessed rather differently. A vehicle used predominantly for business is generally financed as a commercial asset, which can mean faster assessment and fewer disclosure requirements than consumer lending does, though the final pricing depends on your business profile rather than the vehicle type.
Do I need to be GST registered to finance a work vehicle?
GST registration depends on your turnover rather than on any lending rule. Where you are registered, lenders will expect to see your BAS lodgements alongside the application. Where you are not, tax returns and bank statements carry the weight instead. Neither position prevents ute finance for tradies Perth lenders will write.
How long does approval take for a work vehicle?
A straightforward application with complete documents is often assessed within one or two business days, and sometimes faster again for commercial vehicle lending. Newer ABNs, unusual vehicles or incomplete paperwork will all extend that timeframe. Having your fitout quotes ready at submission avoids an entire second round of assessment later on.
Vehicle Choice and Resale
The unit you choose affects both the ute finance for tradies Perth outcome and what you recover when you replace it.
Conventional dual cab utes and common commercial vans have deep resale markets, which ute finance for tradies Perth lenders like. A highly specialised or unusual vehicle has a narrower market and may attract more caution.
Age matters the same way it does for heavier vehicles, and it is assessed at the end of the loan term rather than at purchase. A seven year old ute on a five year term is twelve at the end.
Heavy or permanent fitout can affect resale, since a buyer wanting a standard vehicle sees work to undo. Modular systems that can be removed tend to hold value better than welded installations.
None of this should override what the work actually requires. But if two vehicles both do the job, the one with the better resale market usually finances more easily.
Building Toward the Next Vehicle
The first ute finance for tradies Perth application is the hardest. Everything after it is easier, and it is worth structuring with that in mind.
Twelve months of clean repayment history is genuine evidence for the next ute finance for tradies Perth application. Lenders can see how the business services debt rather than guessing.
Keeping business and personal banking separate makes every subsequent application faster, because the financials are readable.
And if a home purchase is anywhere on the horizon, say so before arranging vehicle finance. The repayment counts as a commitment when a mortgage lender assesses you, and the sequence matters.
What to Prepare
Assembling a ute finance for tradies Perth file properly takes one afternoon and it is the difference between a fast approval and a slow one.
Identification, ABN and GST details, bank statements, financials or a declaration depending on the route, and quotes for both the vehicle and the fitout.
| ABN age | Lender panel | Deposit | What helps most |
|---|---|---|---|
| Two years or more | Widest | Lowest | Clean financials |
| One to two years | Narrower | Higher | Property ownership |
| Under twelve months | Limited | Highest | Trade experience |
| Any age | Depends on conduct | Depends | Clean credit file |
The last row cuts across all of them. Recent enquiries and arrears narrow the panel faster than a young ABN does. Our comparison calculator shows what a larger deposit does to the repayment.
Financing the Fitout, or Not
Financed with the vehicle | Paid separately | |
|---|---|---|
Cost | Vehicle finance pricing | Card or personal loan pricing |
Timing | Quotes needed before applying | Arranged after delivery |
The only real cost of including it is getting the quotes early. For heavier units the same logic applies through truck finance instead.
EXPERT INSIGHT
Amrinder Singh, Specialist Broker at Ezy Loans Australia
“Get the fitout quotes before you apply. Ute finance for tradies Perth wide should cover the working vehicle, not just the vehicle. Adding it later costs several times more.”
If a home purchase is coming, mention it early. A work vehicle repayment affects self employed home lending capacity more than most tradies expect.
FREQUENTLY ASKED QUESTIONS
Everything Perth Tradies Ask,About Work Vehicle Finance
Should the ute be in the business name or mine?
For a vehicle used predominantly for business, the business name is usually the right answer for both tax and finance purposes. Commercial lending is often quicker to assess than consumer lending too. The ownership question has tax consequences beyond the loan, so confirm it with your accountant first.
Can I finance a second-hand work ute?
Yes, and used work vehicles are commonly financed. Age limits apply and are measured at the end of the loan term rather than at purchase. A well maintained unit with service history supports a stronger valuation, which matters more on older vehicles than newer ones.
Does signage and branding count as part of the fitout?
Usually yes. Signage, wraps, shelving, drawer systems and racks are generally treated as part of the vehicle fitout and can be financed alongside it. Include the quotes with your application rather than adding them afterwards, since a variation after approval means reassessment.
What insurance do I need on a work vehicle?
Comprehensive motor insurance is standard and the financier is usually noted as an interested party. Depending on your trade you may also need public liability, tool cover and goods in transit. Check whether your policy covers the fitout, since standard cover sometimes excludes aftermarket additions.
Can I trade in my current ute as the deposit?
Often yes. Trade-in equity is commonly used as the deposit, provided any existing finance on that vehicle is settled at the same time. Confirm the payout figure on your current loan early, because a shortfall between trade value and payout has to be covered from your own funds.
Will this affect my ability to buy a home?
Yes, and it is worth planning the sequence. The vehicle repayment counts as a commitment when a mortgage lender assesses your capacity. Some lenders exclude clearly business-owned assets serviced from business income, but not all. Mention any property plans before arranging the vehicle finance.
Ute finance for tradies Perth businesses need should fund the working vehicle rather than just the vehicle. Ezy Loans Australia arranges the fitout alongside it through our commercial vehicle service, across specialist asset financiers rather than one bank. The first conversation is free.
Written by Amrinder Singh
Amrinder Singh is a Specialist Broker and the founder of Ezy Loans Australia, working from 905 Hay Street in Perth. He arranges first home, refinance, investment, construction, self employed, personal and asset finance across a panel of Australian lenders, and holds Credit Representative number 505232 under Australian Credit Licence 377294. Bring the fitout quotes to the first conversation.
Disclaimer: This article is provided for general information only and does not take into account your objectives, financial situation or needs. Lender criteria, deposit requirements and vehicle age limits differ between financiers and change without notice. This is not tax advice. Consider whether the information is appropriate for you and seek professional advice before acting. Credit assistance is provided by Amrinder Singh, Credit Representative 505232, authorised under Australian Credit Licence 377294 held by Mortgage Australia Group Pty Ltd.
Ezy Loans Australia is a Perth-based mortgage and finance brokerage helping first home buyers, investors and refinancers across Australia secure the right loan with confidence.
Contact Info:
- 905 Hay St, Perth WA 6000
- amrinder@ezyloansaustralia.com.au
- 0432 066 362