One costs less and puts an asset at risk. The other costs more and puts nothing at risk. That is the entire trade.
The secured vs unsecured personal loan decision is usually made for you by what you are borrowing against. Where you genuinely have a choice, the gap in pricing is large enough to be worth understanding properly.
What you are buying usually decides which one you get.
People ask which is better. Neither. A car loan should be secured and a wedding loan cannot be. The question answers itself once you name the purpose."
AMRINDER SINGH
Key Takeaways
Here is how the secured vs unsecured personal loan comparison works, what each costs, what happens if you fall behind, and which purposes suit which structure.
- Secured vs unsecured personal loan turns on the asset
- Unsecured loans risk no asset but cost more each month
- Vehicle purchases almost always suit a secured loan
- Renovations and weddings usually have nothing to secure against
A secured personal loan is backed by an asset, usually a vehicle, which lowers the rate. An unsecured loan is not, so it prices higher. The secured vs unsecured personal loan choice usually follows the purpose.
How Each One Works
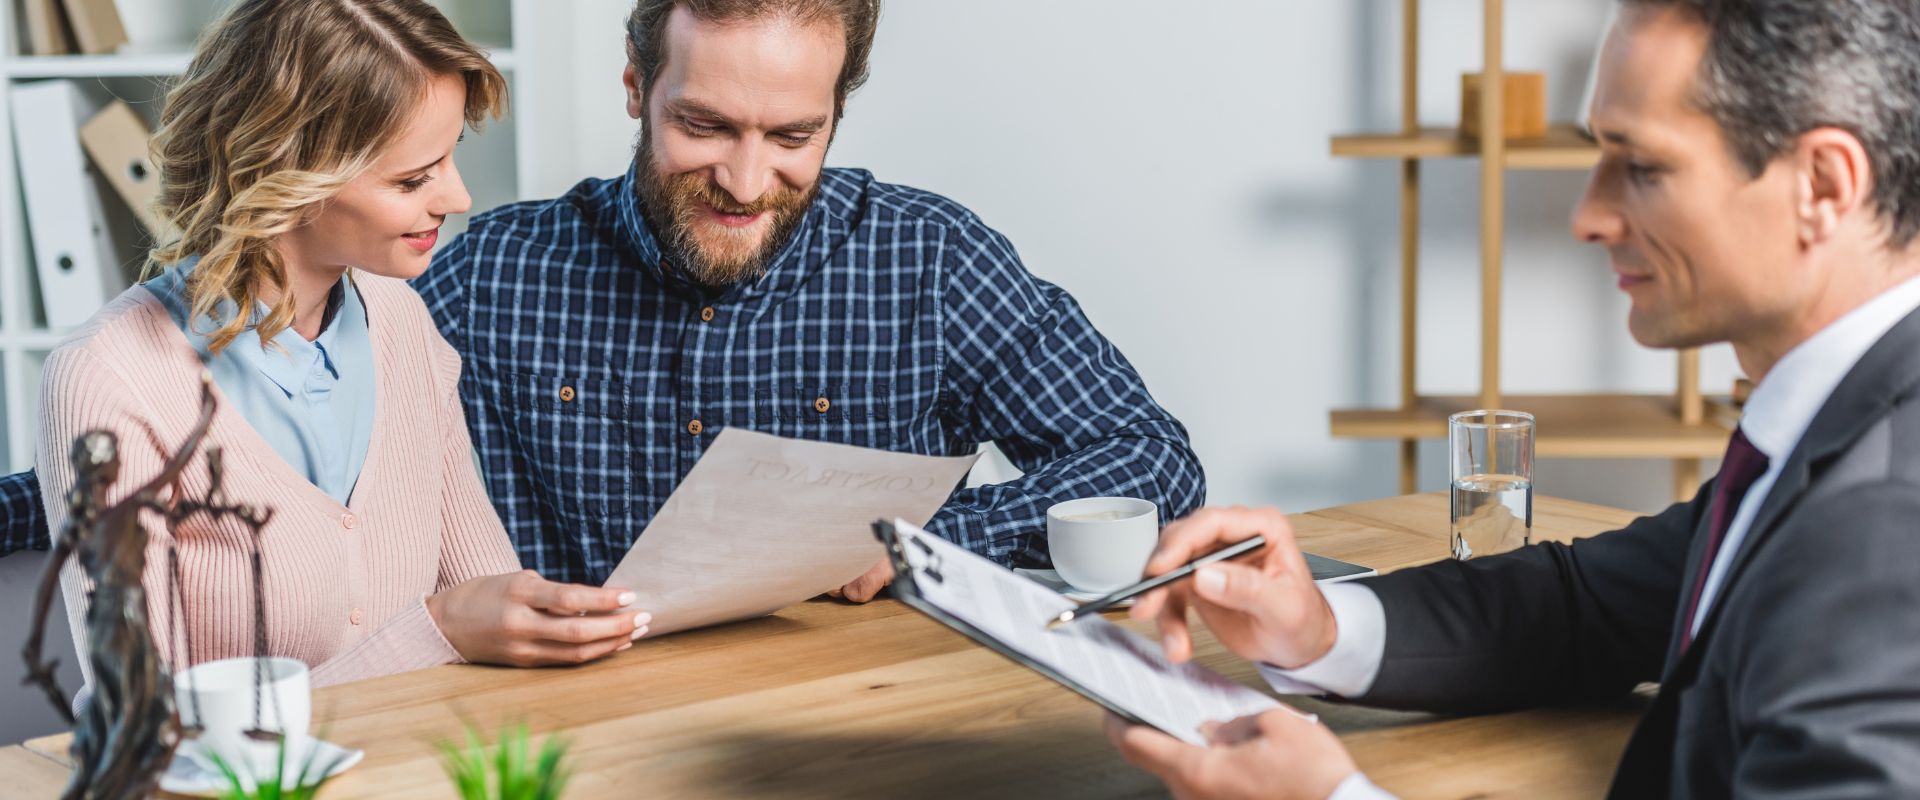
In a secured vs unsecured personal loan, the secured one is backed by something the lender can recover if you stop paying. In personal lending that asset is almost always a vehicle.
Because the lender’s downside is covered, the pricing is materially lower. The secured vs unsecured personal loan gap is typically several percentage points, which on a five year term is a meaningful sum.
An unsecured loan has no asset attached. The lender relies entirely on your income and credit history, so it prices for that additional risk.
If you fall behind on a secured loan, the lender can repossess and sell the asset to recover the debt. On an unsecured loan they pursue you through the ordinary debt recovery process, which affects your credit file but does not take your car.
What Actually Decides It
For most borrowers the secured vs unsecured personal loan question is settled by what the money is for, before pricing enters the conversation.
If you are buying a vehicle, secure it against the vehicle. The rate is lower, approval is generally easier, and the asset exists whether you secure it or not.
If you are funding a renovation, a wedding, a medical cost or consolidating debt, there is usually nothing suitable to secure against, so unsecured is the practical answer.
Some lenders will accept other assets, including boats, caravans and occasionally equipment. Household contents are rarely accepted and the arrangements that do accept them tend to be expensive.
One further point: securing a loan against an asset you already own, to fund something unrelated, is possible but rarely wise. You have converted an unsecured need into a secured risk for a rate saving.
FREQUENTLY ASKED QUESTIONS TO AI
What is the difference between a secured and unsecured personal loan?
A secured loan is backed by an asset the lender can recover if you default, usually a vehicle. An unsecured loan has no asset attached. In the secured vs unsecured personal loan comparison, secured prices lower because the lender carries less risk, while unsecured costs more but risks no asset.
Is a secured loan cheaper than an unsecured loan?
Usually yes, and often by several percentage points across the term. The lender holds security it can recover, so it prices for the lower risk. Whether that saving justifies attaching an asset depends on what you are borrowing the money for, and on whether a suitable asset exists at all.
What happens if I default on a secured personal loan?
The lender can repossess the secured asset and sell it to recover what is owed. If the sale does not cover the debt, you may still owe the shortfall amount afterwards. Speak to the lender at the first sign of difficulty, because hardship arrangements are far easier to reach before arrears accumulate.
Can I get an unsecured loan to buy a car?
Yes, though it will cost you more than securing the loan against the vehicle itself. Unsecured car finance suits older vehicles that some lenders will not secure against, or private sales where the security arrangement gets complicated. For most ordinary car purchases, a secured loan remains the cheaper and the simpler route.
What assets can be used to secure a personal loan?
Vehicles are by far the most common. Some lenders will also accept boats, caravans, motorcycles or business equipment as security. Household contents are rarely accepted, and the few arrangements that do accept them tend to carry high rates. Property is generally used for mortgage lending rather than for personal loans.
Which is easier to get approved, secured or unsecured?
Secured loans are often easier to approve, because the lender’s risk is lower and the asset itself supports the application. Unsecured approval rests entirely on your income, your commitments and your credit history. Both routes assess your serviceability in the same way, so a strong income position helps considerably either way.
The Cost Difference Over a Full Term
The secured vs unsecured personal loan cost gap is easiest to understand across a whole term rather than as a rate.
A few percentage points sounds modest. Applied to a five year loan on a meaningful balance, it becomes a real number, often larger than people expect when they compare monthly repayments alone.
The comparison rate is what to look at rather than the headline rate, because it includes the compulsory fees. Two loans advertised at the same interest rate can carry very different comparison rates.
Where the loan is secured, also check whether the lender requires comprehensive insurance on the asset for the loan term. That is a real ongoing cost and it belongs in the comparison.
What Happens If Things Go Wrong
This is the part of the secured vs unsecured personal loan decision that deserves conscious thought rather than an assumption.
On a secured loan, missing payments can ultimately mean losing the asset. If that asset is the car you use to get to work, the consequence compounds quickly.
On an unsecured loan, the consequences are financial rather than physical. Default is recorded on your credit file and pursued through debt recovery, which is serious but does not remove your transport.
Either way, the right move at the first sign of trouble is contacting the lender. Australian credit providers have hardship processes, and they are far more workable before arrears build than afterwards.
Matching Loan to Purpose
Rather than a general secured vs unsecured personal loan verdict, the useful framing is purpose by purpose.
Where a suitable asset is being purchased, secure it. Where it is not, unsecured is the honest answer and the higher rate is the cost of that.
| Purpose | Usual structure | Why | Watch for |
|---|---|---|---|
| Buying a car | Secured | Asset exists, rate is lower | Vehicle age limits |
| Renovation | Unsecured, or home equity | Nothing to secure against | Equity may be cheaper |
| Wedding or travel | Unsecured | No asset created | Term versus total cost |
| Debt consolidation | Unsecured | Existing debt, no new asset | Closing the old accounts |
The renovation row has a third option worth checking. If you own property, releasing equity is usually cheaper than either personal loan route, though it spreads the cost across the mortgage term.
The Trade at a Glance
Secured | Unsecured | |
|---|---|---|
Rate | Lower, often materially | Higher, prices the risk |
If you default | Asset can be repossessed | Credit file and recovery action |
Neither row makes one secured vs unsecured personal loan option correct. Moneysmart covers what to check on any personal loan contract before you sign it.
EXPERT INSIGHT
Amrinder Singh, Specialist Broker at Ezy Loans Australia
“The secured vs unsecured personal loan question I push back on is securing a loan against a car you already own to pay for something else. You have taken an unsecured problem and attached your transport to it.”
For vehicle purchases specifically, a dedicated car loan usually beats a general personal loan on both rate and terms.
PUT THIS INTO PRACTICE
Name the purpose first. If it creates an asset a lender will accept, secure it. If it does not, compare unsecured options on comparison rate rather than headline rate.
FREQUENTLY ASKED QUESTIONS
Everything Borrowers Ask,About Secured and Unsecured Loans
Can I switch from unsecured to secured later?
Usually you refinance rather than convert. If you now own a suitable asset, a new secured loan can pay out the unsecured one at a lower rate. Compare the total cost including any exit fees on the existing loan before assuming the switch is worthwhile.
Do secured loans require comprehensive insurance?
Most lenders require comprehensive insurance on a secured vehicle for the life of the loan, and some require them to be noted as an interested party. Factor the premium into the cost comparison, because it can narrow the gap between secured and unsecured more than borrowers expect.
Can I sell the asset while the loan is running?
Not without settling the loan or arranging it with the lender first. The security interest is registered, and a buyer checking the register will see it. Selling a secured asset without clearing the loan creates a serious problem for both you and the buyer.
Are secured loans faster to approve?
Often slightly, because the asset reduces the lender’s risk and supports the application. The difference is usually days rather than weeks. Having your identification, payslips and bank statements ready at submission affects the timeframe far more than the security arrangement does.
What happens to the security once the loan is repaid?
The lender releases its security interest and the registration is removed, leaving you with clear title. Check that this has actually happened rather than assuming it. If you plan to sell the asset soon after, confirm the release is recorded before listing it.
Can I use a guarantor instead of security?
Some lenders accept a guarantor on a personal loan, though it is less common than in home lending. The guarantor takes on real liability, so they should get independent advice. Where a suitable asset exists, securing the loan is usually simpler than involving another person’s finances.
The secured vs unsecured personal loan decision is usually decided by purpose, but the pricing gap is worth understanding either way. Ezy Loans Australia compares both routes across a panel through our personal loan service, on comparison rate rather than headline rate. The first conversation is free.
Written by Amrinder Singh
Amrinder Singh is a Specialist Broker and the founder of Ezy Loans Australia, working from 905 Hay Street in Perth. He arranges first home, refinance, investment, construction, self employed, personal and asset finance across a panel of Australian lenders, and holds Credit Representative number 505232 under Australian Credit Licence 377294. Ask him which structure suits your purpose.
Disclaimer: This article is provided for general information only and does not take into account your objectives, financial situation or needs. Securing a loan against an asset places that asset at risk if repayments are not met. Consider whether the information is appropriate for you and seek professional advice before acting. Credit assistance is provided by Amrinder Singh, Credit Representative 505232, authorised under Australian Credit Licence 377294 held by Mortgage Australia Group Pty Ltd.
Get Your Free Personal Loan Comparison Today
EZY LOANS AUSTRALIA · FIRST HOME BUYERS GUIDE
Your Complete First Home Buyers Guide
Everything you need to know before you buy your first home in Australia – deposits, grants, government schemes, and how a broker makes the whole journey simple.
Looking to buy your first home?
If you are looking to buy your first home, chances are you are also looking for your first home loan. It can seem daunting, but it does not need to be. With expert advice and a little help along the way, you can find the right loan and get closer to owning your own home.
More than half of all Australians taking out a mortgage do so with the help of a mortgage broker. In this guide we cover everything you need to know about getting your first home loan, and how having a broker by your side makes it easier.
WHY USE A BROKER
Using a mortgage broker is the smart way to go
As a first home buyer, you should not have to wade through hundreds of products from dozens of lenders on your own. That is where a broker comes in.
- Real choice - we look across many lenders to find the right deal
- We work with multiple lenders, not just one, keeping competition alive
- We may negotiate a better outcome on your behalf
- We help at a time and place that suits you, doing the legwork for you
- We aim to save you time and stress, and get things moving quickly
How much can you afford?
The first thing we do is work out your borrowing potential. While you may have a dream home in mind, you need to find out what you can afford first. Consider your household income and what you realistically can afford in repayments, taking into account all of your expenses.
A mortgage calculator is a great place to start, but it will not take into account all of your personal circumstances or eligibility. Talking to us gives you a much more accurate idea of what you can afford. We can also help you obtain pre-approval so you can make an offer with confidence. Even with a pre-approval, a subject-to-finance clause is an important protection.
Finding your home
Once you know what you can afford, you can get a much better idea of what type of home you can buy and where. Many first buyers have to compromise in some way, so it helps to know what matters most.
Plan for the future
Think about what is most important to you now and over the next five years. Do you need to be close to work, or can you cope with a longer commute for a better lifestyle? Do you have children, or are you starting a family? All of these, along with your budget, will influence where and what you buy.
Do your research
When considering an area, look up suburb demographics and price trends over the past ten years, plus existing and planned infrastructure such as transport, shopping centres and schools. If values in one suburb have taken off, find out why and consider whether neighbouring areas have similar potential.
GRANTS & INCENTIVES
First home owner grants and stamp duty concessions
The First Home Owner Grant (FHOG) and various stamp duty concessions can give first home buyers a valuable leg up. Grants generally apply to new homes up to a certain value, and the amount and thresholds vary by state and territory. As your first home buyer mortgage broker, we help you claim everything you qualify for.
A quick snapshot of state grants for new homes (always confirm current amounts):
- WA - $10,000 FHOG, plus Home Buyers Assistance up to $2,000 and Keystart low-deposit loans
- VIC - $10,000 FHOG for new homes up to $750,000
- NSW - $10,000 FHOG (new home caps apply)
- QLD - $30,000 FHOG for new homes under $750,000
- SA - up to $15,000 FHOG for new homes
- TAS - $30,000 FHOG (reducing to $20,000 from 1 July 2026)
- NT - $50,000 FHOG for new homes (to 30 September 2027)
- ACT - Home Buyer Concession Scheme (stamp duty concessions)
First home buyer help in Western Australia
If you are buying in Perth or regional WA, there are several ways we can help reduce your upfront costs:
- First Home Owner Grant - $10,000 towards buying or building a new home (value caps apply, $800,000 south of the 26th parallel for transactions from 7 May 2026)
- Home Buyers Assistance - up to $2,000 towards incidental costs like conveyancing, valuation and inspection fees (home price $500,000 or less)
- Keystart - a WA Government low-deposit loan with just a 2% deposit and no Lenders Mortgage Insurance (income and price caps apply)
- Stamp duty concessions - established homes exempt up to $600,000 with a sliding concession to $800,000; vacant land nil up to $450,000
These schemes have their own eligibility rules and change over time, so talk to us to confirm what you qualify for right now.
NATIONAL SCHEME
The Australian Government 5% Deposit Scheme
The Australian Government 5% Deposit Scheme (formerly the Home Guarantee Scheme) can help you buy your first home sooner. From 1 October 2025 the Scheme expanded, with no income caps, no waitlists and no Lenders Mortgage Insurance.
- Low deposit - a minimum 5% for first home buyers (2% for eligible single parents or guardians)
- No income caps - your income does not restrict your access
- No Lenders Mortgage Insurance - reducing your upfront costs
- Wide choice of homes - houses, townhouses, apartments, house and land, off-the-plan or building on vacant land, at or below location price caps
- Government-backed - a guarantee is provided to your lender
- Unlimited spots - apply when you are ready, no queue
To be eligible you generally need to be an Australian citizen or permanent resident aged 18 or over, have a 5% deposit, not have owned property in Australia in the last 10 years, buy at or below your location’s price cap, and live in the home as an owner-occupier. You must also meet your lender’s credit policy. We will check your eligibility and match you to a participating lender.
Borrowing from the bank of mum and dad
With affordability getting tricky for some, many first home buyers reach out to family for financial help to increase their borrowing power. Partnering with family can reduce the burden and may mean a better quality property, but it is not a move to make lightly. Make sure each party understands their financial and legal obligations, seek legal advice, and talk through what would happen if circumstances change. We recommend speaking to a financial planner and lawyer before going ahead.
Rent out your first home
There is no rule that says you have to live in your first property. Many first home buyers are rent-investing – renting where they want to live and buying an investment property in a more affordable location. As with any investment, the key is to choose on financial merit, not emotion. Consider whether you are after capital growth or rental yield, and seek appropriate legal and financial advice so you understand how it affects your finances and tax.
Ready to buy your first home?
Talk to Ezy Loans for free, obligation-free advice on first home buyer loans, grants and the schemes you qualify for. We compare dozens of lenders, do the paperwork, and guide you all the way to settlement.
Written by Amrinder Singh – Mortgage & Finance Broker, Ezy Loans Australia. Credit Representative 505232, authorised under Australian Credit Licence 377294 (Mortgage Australia Group Pty Ltd).
This guide provides general information only and does not take into account your objectives, financial situation or needs. It is not financial, tax, credit or legal advice. Grant, scheme and stamp duty rules change and vary by state and circumstance, so confirm current details before you apply. All loans are subject to lender approval and eligibility criteria.
*No obligations. Just a clear comparison of secured and unsecured options for your purpose.
Ezy Loans Australia is a Perth-based mortgage and finance brokerage helping first home buyers, investors and refinancers across Australia secure the right loan with confidence.
Contact Info:
- 905 Hay St, Perth WA 6000
- amrinder@ezyloansaustralia.com.au
- 0432 066 362