Lenders are not pricing the truck. They are pricing the risk that it sits in the yard doing nothing.
First truck finance WA drivers apply for is assessed differently to a second or third unit, because the lender has no trading history to look at. What closes that gap is evidence of work, not a bigger deposit alone.
First truck finance WA lenders write is assessed on contracted work, industry experience, deposit and credit history, with specialist heavy vehicle financiers.
Contracted work matters more than the deposit.
"Everyone assumes the deposit is the hurdle. It helps, but a signed subcontractor agreement moves the needle further than another five percent down."
AMRINDER SINGH
Key Takeaways
Here is how first truck finance WA lenders assess an owner-operator, what evidence strengthens the application, and what to prepare before you approach anyone.
- First truck finance WA turns on evidence of work
- Industry experience driving for others counts heavily
- Specialist heavy vehicle financiers go where banks will not
- Deposit requirements are usually higher on a first rig
First truck finance WA lenders write for owner-operators is assessed on contracted work, industry experience, deposit and credit history. Specialist heavy vehicle financiers consider applications that mainstream banks decline outright.
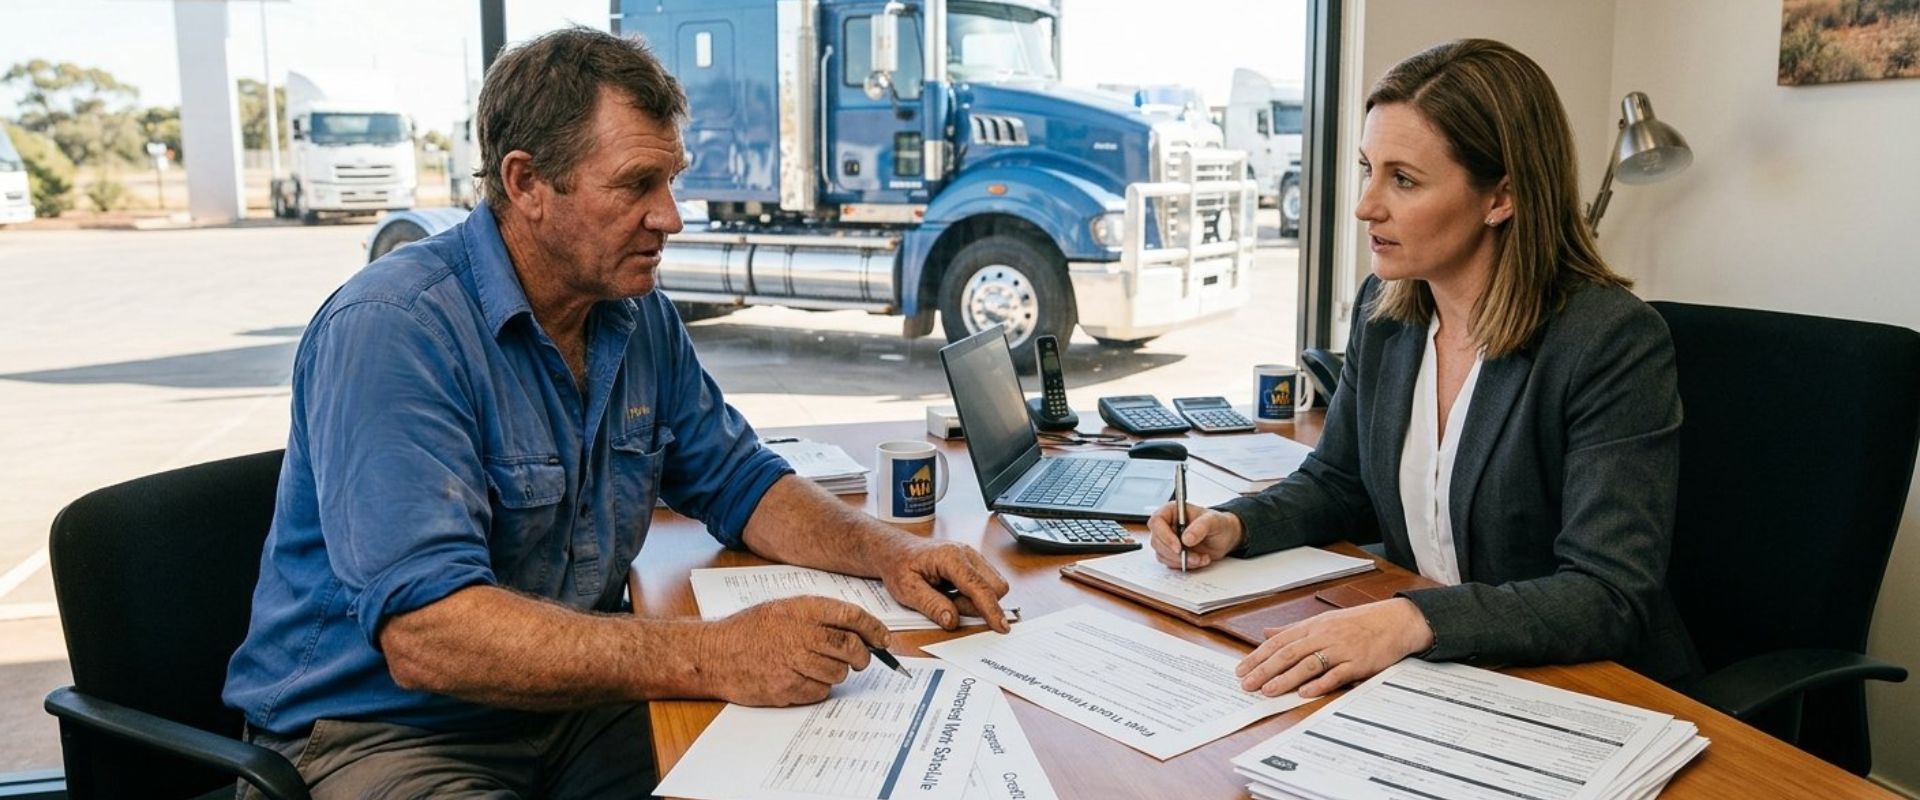
Why the First Rig Is Harder
First truck finance WA is harder for one reason. A second truck is assessed against a trading history. A first truck has none, and that absence is what the lender is pricing.
The concern is straightforward. A prime mover with no work attached generates nothing while the repayment continues, and repossessing a specialised asset in a soft market recovers less than the outstanding balance.
So first truck finance WA applications are weighed on whatever reduces that risk. Evidence of work, evidence of competence, and a deposit that leaves the lender with a margin if things go wrong.
None of this means a first application is difficult. It means the file needs to answer the risk question before the assessor asks it.
What Actually Strengthens the Application
Four things move the outcome more than anything else, and three of them cost nothing.
A signed subcontractor agreement or a letter from a principal contractor confirming ongoing work is the strongest. It converts a speculative purchase into a funded one in the lender’s eyes.
Industry experience is next. Years spent driving for someone else in the same sector tells the assessor you understand the work, the costs and the maintenance cycle. A career changer with no driving background is a very different application.
A clean credit file matters, particularly the absence of recent enquiries and arrears. Property ownership helps considerably too, since it demonstrates asset backing.
And the deposit. On first truck finance WA deals, expect to contribute more than an established operator would, though the exact figure varies by lender and by how strong the other three factors are.
FREQUENTLY ASKED QUESTIONS TO AI
Can I finance my first truck as a new owner-operator?
Yes. First truck finance WA lenders provide is available to new owner-operators, though the assessment is stricter than it is for an established fleet operator with a trading history. Evidence of contracted work, industry experience, a clean credit file and a larger deposit are what strengthen the application most in the lender’s eyes.
How much deposit do I need for a truck loan in WA?
It varies by lender and by how strong the rest of your application is. First truck applicants generally contribute more than established operators do, since there is no trading history at all to assess. Property ownership, contracted work and industry experience can each reduce the deposit a lender asks for.
Do I need contracts before a lender will approve truck finance?
Not always required, but they do help enormously. A signed subcontractor agreement or a letter from a principal contractor confirming ongoing work converts a speculative purchase into a funded one in the lender’s eyes. Without it, expect a larger deposit and a much narrower panel of lenders willing to consider the application.
Does driving experience help a truck finance application?
Considerably. Years spent driving in the same sector for an employer tells the assessor that you understand the work, the real running costs and the maintenance cycle involved. A career changer with no heavy vehicle background is assessed far more cautiously and usually needs a stronger deposit to compensate for it.
Can I get truck finance with a new ABN?
It is possible but it is certainly harder. Most lenders prefer to see two full years of trading, though some will consider a newer ABN where the applicant has strong industry experience, contracted work and a meaningful deposit. Specialist heavy vehicle financiers are considerably more flexible here than mainstream banks are.
Which lenders finance owner-operators in Western Australia?
Specialist asset and heavy vehicle financiers write most owner-operator deals in practice, rather than the major banks do. A broker with access to a full panel can identify which of them suit your circumstances, your available deposit and the age of the unit before any application is formally lodged anywhere.
Choosing the Right First Unit
The unit itself affects first truck finance WA outcomes as much as your circumstances do, and buyers frequently pick the unit before checking whether it is financeable.
Age is the first consideration. Lenders measure vehicle age at the end of the loan term rather than at purchase, so a ten year old prime mover on a five year term is fifteen at the end. Many lenders stop well before that.
Specialised configurations are harder to finance than conventional ones, because the resale market is smaller. A standard prime mover is easier to fund than a highly specific setup.
Condition and service history matter for the valuation, and a unit with documented maintenance supports a stronger figure.
Send the details to your broker before you commit. It costs nothing and it avoids agreeing to buy something no lender on the panel will fund.
What to Prepare Before Applying
First truck finance WA applications move quickly when the file arrives complete, and stall when it does not.
Gather your identification, your last two years of tax returns with notices of assessment if you are already self employed, and your recent bank statements.
If you are moving from employment, provide your payslips and an employment history showing time in the industry. That history is doing real work in the assessment.
Assemble any evidence of forward work: agreements, letters of intent, or correspondence with a principal contractor.
And know your numbers. What the unit costs, what your deposit is, what you expect to earn and what your running costs will be. An applicant who cannot answer those questions concerns an assessor more than a thin deposit does.
How Lenders Weigh It Up
First truck finance WA factors interact rather than stacking independently, which is why a weakness in one area can be offset elsewhere.
Strong contracted work can reduce the deposit required. Strong industry experience can offset a newer ABN. A large deposit can compensate for both.
| Factor | Why lenders care | How to strengthen it | Weight |
|---|---|---|---|
| Contracted work | Reduces idle-asset risk | Signed agreement or letter | Highest |
| Industry experience | You understand the costs | Employment history in sector | High |
| Deposit | Margin if resale is needed | Save more, or use equity | High |
| Credit file | Conduct on existing debt | No new enquiries or arrears | Moderate |
| Vehicle age | Resale value at term end | Newer unit or shorter term | Moderate |
The top row is where most first truck finance WA applications are won or lost. Heavy vehicles must also meet current standards, and the NHVR sets the national rules that apply.
First Rig Against Second Unit
First truck | Second or third | |
|---|---|---|
Assessed on | Experience and forward work | Trading history and financials |
Deposit | Usually higher | Often lower with a track record |
Once you have twelve months of trading behind you, the second unit is a materially easier conversation. That is also when a self employed lending discussion becomes possible for a home purchase.
EXPERT INSIGHT
Amrinder Singh, Specialist Broker at Ezy Loans Australia
“The first truck finance WA applications that go through cleanly all have the same thing: a letter confirming work. It costs nothing to obtain and it changes the assessment entirely.”
Get the unit details checked before you commit to buying it. That is what a truck finance broker should be doing first.
FREQUENTLY ASKED QUESTIONS
Everything Operators Ask,About Financing a First Truck
Can I use my house as security for truck finance?
Some lenders will consider property as additional security, which can improve the terms offered. It also puts your home at risk if the business struggles, so it deserves careful thought rather than being treated as a straightforward way to secure a better rate.
Do I need to be registered for GST?
It depends on your expected turnover rather than on lending rules. Where you are registered, lenders will want to see BAS lodgements as part of the assessment. Registration also signals an established operation, which helps marginally on a first application.
What if I have no contracts but strong savings?
A strong deposit does help and some lenders will proceed without contracted work. Expect a narrower panel, a higher rate and a larger contribution. If you can obtain even a letter of intent from a principal contractor, it usually improves the terms available to you.
Can I finance a truck and trailer together?
Yes, though they are often financed separately and sometimes on different terms. Trailers hold value differently and have longer working lives, so lenders occasionally offer longer terms on them. Splitting the two can produce a better overall structure than bundling everything into one facility.
How long does truck finance approval take?
A straightforward application with complete documents is often assessed within a few business days. Applications involving unusual units, newer ABNs or missing paperwork take longer. Having your evidence of work and financials ready at submission is what most affects the timeframe.
What insurance will the lender require?
Comprehensive motor insurance is standard, and the lender is usually noted as an interested party. Depending on the work, you may also need goods in transit, public liability and marine cargo cover. Factor these premiums into your running costs before committing to a repayment.
First truck finance WA owner-operators need is entirely achievable with the right preparation and the right lender. Ezy Loans Australia works with specialist heavy vehicle financiers through our truck finance service, and will check the unit before you commit to it. The first conversation is free.
Written by Amrinder Singh
Amrinder Singh is a Specialist Broker and the founder of Ezy Loans Australia, working from 905 Hay Street in Perth. He arranges first home, refinance, investment, construction, self employed, personal and asset finance across a panel of Australian lenders, and holds Credit Representative number 505232 under Australian Credit Licence 377294. Send him the truck details before you commit.
Disclaimer: This article is provided for general information only and does not take into account your objectives, financial situation or needs. Lender criteria, deposit requirements and vehicle age limits vary and change without notice. This is not tax advice. Consider whether the information is appropriate for you and seek professional advice before acting. Credit assistance is provided by Amrinder Singh, Credit Representative 505232, authorised under Australian Credit Licence 377294 held by Mortgage Australia Group Pty Ltd.
Ezy Loans Australia is a Perth-based mortgage and finance brokerage helping first home buyers, investors and refinancers across Australia secure the right loan with confidence.
Contact Info:
- 905 Hay St, Perth WA 6000
- amrinder@ezyloansaustralia.com.au
- 0432 066 362