Consolidation lowers what you pay each month. Whether it lowers what you pay in total is a different question.
Debt consolidation Australia lenders offer rolls several debts into one loan with one rate and one repayment. It genuinely helps a great many people. It also quietly costs some of them more, and the difference comes down to two things nobody checks.
The monthly figure and the total cost move in opposite directions.
"Consolidation only works if the spending that created the debt stops. Otherwise you have cleared the cards and kept the habit, and in a year there are cards again plus a loan."
AMRINDER SINGH
Key Takeaways
Here is how debt consolidation Australia borrowers use actually works, when it saves money, when it only appears to, and the behavioural condition that decides the outcome.
- Debt consolidation Australia replaces several debts with one
- A longer term can raise the total cost while lowering the monthly
- It only works if the accounts are closed afterwards
- Rolling debt into a mortgage stretches it across decades
Debt consolidation Australia lenders provide combines multiple debts into a single loan at one rate. It usually lowers the monthly repayment and simplifies management, but a longer term can increase the total interest paid.
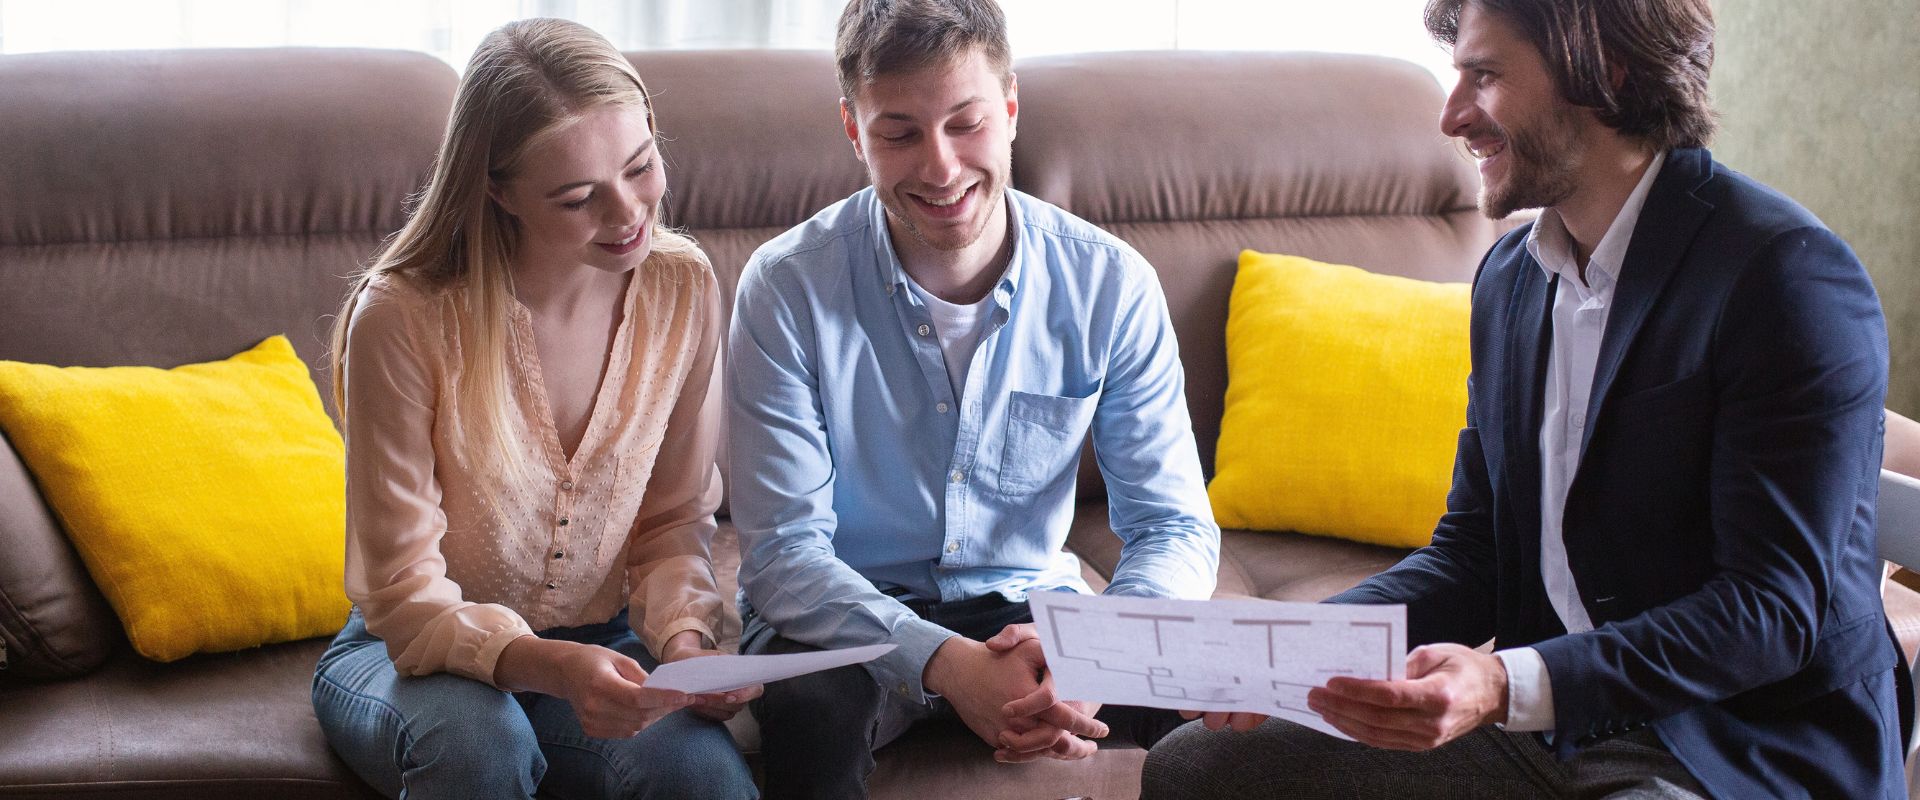
What Consolidation Actually Changes
Three things change with debt consolidation Australia borrowers arrange, and only two of them are unambiguously good.
The rate changes. Credit cards and store cards sit at the expensive end of the market, so replacing them with a personal loan almost always reduces the interest rate you pay on that balance.
The structure changes. Several due dates, several minimum payments and several statements become one fixed repayment with a defined end date. For people juggling multiple accounts, that alone reduces the risk of a missed payment.
The term changes, and this is the one to watch. Credit card debt has no fixed end date, so consolidating it into a five year loan actually creates one. But rolling that same debt into a mortgage spreads it across twenty five years, and the total interest can exceed what the cards would have cost.
When It Genuinely Saves Money
Debt consolidation Australia borrowers benefit from most has a clear profile, and it is worth checking whether you fit it.
You have multiple debts at rates meaningfully higher than the consolidation loan you can access. The larger that gap, the stronger the case.
You can service the new repayment comfortably. Consolidation that stretches your budget to breaking point has solved nothing, it has just rearranged the pressure.
You will close the accounts afterwards and keep them closed. This is the condition that decides the outcome more than any rate does.
And the term is shorter or similar to what you would otherwise have taken to clear the debts. Where the term stretches significantly, run the total cost before agreeing to anything.
FREQUENTLY ASKED QUESTIONS TO AI
Is debt consolidation a good idea in Australia?
It depends on the gap between your current rates and the consolidation rate, and on whether you close the accounts afterwards. Debt consolidation Australia lenders offer usually lowers the monthly repayment and simplifies management of your debts, but a longer term can increase the total interest you end up paying overall.
Does debt consolidation hurt your credit score?
Short term it may dip slightly, because the application records a credit enquiry. Longer term it often improves, since consistent repayments on a single loan build a cleaner history than several accounts with variable conduct. Closing the old accounts and then keeping them closed is what actually drives that longer term improvement.
Can I consolidate debt into my home loan?
Yes, and it is common. The rate is far lower than card or personal loan rates, which is genuinely attractive. The trade-off is the term: debt spread across a twenty five year mortgage can cost more in total interest than clearing it over five years, even at a much higher rate.
What debts can be consolidated?
Credit cards, store cards, personal loans, car loans, buy now pay later balances and sometimes tax debt can all be consolidated, depending on the lender. Secured debts such as car loans may need the security released or refinanced. Each lender has its own list, so check before assuming everything qualifies.
Will I be approved for a debt consolidation loan?
Lenders assess your income, existing commitments, credit history and the reason for consolidating. A history of missed payments makes approval harder but not impossible, since specialist lenders will consider impaired files. Applying to several lenders directly damages your position, so get your circumstances properly assessed by a broker before anything is lodged.
Is it better to consolidate or pay debts off individually?
Consolidating suits people with several high rate debts who want one manageable repayment and a clear end date. Paying individually suits those with one or two debts, or the discipline to target the highest rate first. Compare the total cost of both approaches carefully rather than looking only at the monthly figure.
When It Costs You More
The debt consolidation Australia failure modes are predictable, which means they are avoidable.
The most common is the reset. Cards are cleared, the relief is real, and within a year the balances have rebuilt because nothing about the spending changed. Now there is a consolidation loan and card debt.
The second is term stretch. A five year card payoff plan becomes a twenty five year mortgage component. The monthly figure drops sharply and the total cost climbs, sometimes by more than the original debt.
The third is unsecured debt becoming secured. Rolling card debt into a mortgage converts debt that risked your credit file into debt secured against your home. That is a meaningful change in risk that deserves conscious agreement rather than a signature.
The fourth is fees. Establishment fees, early exit costs on the debts being cleared and any ongoing account fee all sit against the saving.
The Behavioural Condition
Every lender will discuss debt consolidation Australia rates. Fewer will raise the thing that actually determines whether debt consolidation Australia borrowers take works.
Consolidation treats the symptom. If the underlying spending pattern continues, the balances return, and the second round is harder because there is now a loan repayment as well.
The practical step is closing the accounts as the debts are cleared, not intending to. Keep the closure confirmations, because a lender assessing you later will ask for evidence rather than take your word.
If the debt arose from a one-off event, a medical cost, a car repair, a period between jobs, consolidation is straightforwardly sensible. If it accumulated gradually through ordinary spending, address that first or the loan simply buys time.
Comparing the Real Cost
The debt consolidation Australia comparison that matters is total cost against total cost, not monthly against monthly.
Take each existing debt, its rate and the time you would realistically take to clear it. Then compare the total interest against the consolidation loan across its full term.
| Route | Typical term | Monthly effect | Total cost effect |
|---|---|---|---|
| Leave as is | Open ended on cards | Several minimums | Highest, no end date |
| Personal loan | Three to seven years | Lower, fixed | Usually lower |
| Into the mortgage | Up to thirty years | Lowest by far | Can be highest |
| Targeted payoff | You control it | Unchanged | Lowest if sustained |
The third row is where debt consolidation Australia borrowers most often go wrong. If you do use the mortgage, pay that portion down deliberately faster than the rest. Our loan comparison calculator shows the difference.
Consolidation Against Renegotiation
Consolidate | Renegotiate first | |
|---|---|---|
Suits you when | Several debts, high rates, clear plan | One or two debts, good conduct |
Cost | Application and possible exit fees | Usually nothing but a phone call |
Before consolidating, call each provider and ask for a hardship or rate reduction arrangement. Moneysmart sets out the free options available, including financial counselling.
EXPERT INSIGHT
Amrinder Singh, Specialist Broker at Ezy Loans Australia
“I have told people not to consolidate more than once. If the plan is a lower repayment and nothing else changes, debt consolidation Australia lenders write will feel better for a year and worse after that.”
Where consolidation is right, the structure matters as much as the rate. Compare it against a standard personal loan before deciding.
PUT THIS INTO PRACTICE
Before any debt consolidation Australia application, list every debt with its balance, rate and minimum payment. Add the total interest if you cleared each one in three years. Compare that against the consolidation loan across its full term.
FREQUENTLY ASKED QUESTIONS
Everything Borrowers Ask,About Consolidating Debt
Can I consolidate if I have missed payments?
Often yes, though the lender panel narrows and pricing rises. Recent or repeated arrears are harder than an isolated one from two years ago. Document the reason and submit it upfront. Specialist lenders consider impaired files where mainstream lenders will not, so the lender choice matters considerably.
Should I close my credit cards after consolidating?
Yes, and keep the closure confirmations. Lenders assessing you later will ask for evidence rather than accept your word. Leaving cards open also leaves the limits in place, and lenders assess credit cards on the limit rather than the balance, which reduces your future borrowing capacity.
Does consolidation affect a future home loan application?
It can help or hurt depending on how you handle it. One consolidation loan with clean repayment history reads better than several accounts with variable conduct. But the repayment counts as a commitment, so it reduces borrowing capacity. Tell your broker if a property purchase is planned.
Can I consolidate a HECS or HELP debt?
No. Study debt is repaid through the tax system and cannot be consolidated into a commercial loan. It does count as a commitment when lenders assess your borrowing capacity, though the impact is usually smaller than borrowers fear because repayments are linked to income.
Is there a minimum amount worth consolidating?
There is no fixed threshold, but small balances rarely justify the application and establishment fees. As a rough guide, consolidation makes sense where the interest saving across the term clearly exceeds the setup costs. Below that, a targeted payoff of the highest rate debt is usually better.
What if my consolidation application is declined?
Ask why before applying elsewhere, because a second application adds another enquiry to your file. Common reasons are serviceability, recent arrears or too many recent enquiries. A broker can identify a lender whose policy fits your circumstances rather than repeating the same application.
Debt consolidation Australia lenders offer works well for the right borrower and poorly for the wrong one. Ezy Loans Australia will run the total cost comparison honestly as part of our personal loan service, including telling you when consolidating is not the right answer. The first conversation is free.
Written by Amrinder Singh
Amrinder Singh is a Specialist Broker and the founder of Ezy Loans Australia, working from 905 Hay Street in Perth. He arranges first home, refinance, investment, construction, self employed, personal and asset finance across a panel of Australian lenders, and holds Credit Representative number 505232 under Australian Credit Licence 377294. Ask him to compare the total cost, not just the repayment.
Disclaimer: This article is provided for general information only and does not take into account your objectives, financial situation or needs. Consolidating debts may extend the term and increase the total interest paid. Free financial counselling is available through the National Debt Helpline. Consider whether the information is appropriate for you and seek professional advice before acting. Credit assistance is provided by Amrinder Singh, Credit Representative 505232, authorised under Australian Credit Licence 377294 held by Mortgage Australia Group Pty Ltd.
Get Your Free Debt Consolidation Review Today
EZY LOANS AUSTRALIA · FIRST HOME BUYERS GUIDE
Your Complete First Home Buyers Guide
Everything you need to know before you buy your first home in Australia – deposits, grants, government schemes, and how a broker makes the whole journey simple.
Looking to buy your first home?
If you are looking to buy your first home, chances are you are also looking for your first home loan. It can seem daunting, but it does not need to be. With expert advice and a little help along the way, you can find the right loan and get closer to owning your own home.
More than half of all Australians taking out a mortgage do so with the help of a mortgage broker. In this guide we cover everything you need to know about getting your first home loan, and how having a broker by your side makes it easier.
WHY USE A BROKER
Using a mortgage broker is the smart way to go
As a first home buyer, you should not have to wade through hundreds of products from dozens of lenders on your own. That is where a broker comes in.
- Real choice - we look across many lenders to find the right deal
- We work with multiple lenders, not just one, keeping competition alive
- We may negotiate a better outcome on your behalf
- We help at a time and place that suits you, doing the legwork for you
- We aim to save you time and stress, and get things moving quickly
How much can you afford?
The first thing we do is work out your borrowing potential. While you may have a dream home in mind, you need to find out what you can afford first. Consider your household income and what you realistically can afford in repayments, taking into account all of your expenses.
A mortgage calculator is a great place to start, but it will not take into account all of your personal circumstances or eligibility. Talking to us gives you a much more accurate idea of what you can afford. We can also help you obtain pre-approval so you can make an offer with confidence. Even with a pre-approval, a subject-to-finance clause is an important protection.
Finding your home
Once you know what you can afford, you can get a much better idea of what type of home you can buy and where. Many first buyers have to compromise in some way, so it helps to know what matters most.
Plan for the future
Think about what is most important to you now and over the next five years. Do you need to be close to work, or can you cope with a longer commute for a better lifestyle? Do you have children, or are you starting a family? All of these, along with your budget, will influence where and what you buy.
Do your research
When considering an area, look up suburb demographics and price trends over the past ten years, plus existing and planned infrastructure such as transport, shopping centres and schools. If values in one suburb have taken off, find out why and consider whether neighbouring areas have similar potential.
GRANTS & INCENTIVES
First home owner grants and stamp duty concessions
The First Home Owner Grant (FHOG) and various stamp duty concessions can give first home buyers a valuable leg up. Grants generally apply to new homes up to a certain value, and the amount and thresholds vary by state and territory. As your first home buyer mortgage broker, we help you claim everything you qualify for.
A quick snapshot of state grants for new homes (always confirm current amounts):
- WA - $10,000 FHOG, plus Home Buyers Assistance up to $2,000 and Keystart low-deposit loans
- VIC - $10,000 FHOG for new homes up to $750,000
- NSW - $10,000 FHOG (new home caps apply)
- QLD - $30,000 FHOG for new homes under $750,000
- SA - up to $15,000 FHOG for new homes
- TAS - $30,000 FHOG (reducing to $20,000 from 1 July 2026)
- NT - $50,000 FHOG for new homes (to 30 September 2027)
- ACT - Home Buyer Concession Scheme (stamp duty concessions)
First home buyer help in Western Australia
If you are buying in Perth or regional WA, there are several ways we can help reduce your upfront costs:
- First Home Owner Grant - $10,000 towards buying or building a new home (value caps apply, $800,000 south of the 26th parallel for transactions from 7 May 2026)
- Home Buyers Assistance - up to $2,000 towards incidental costs like conveyancing, valuation and inspection fees (home price $500,000 or less)
- Keystart - a WA Government low-deposit loan with just a 2% deposit and no Lenders Mortgage Insurance (income and price caps apply)
- Stamp duty concessions - established homes exempt up to $600,000 with a sliding concession to $800,000; vacant land nil up to $450,000
These schemes have their own eligibility rules and change over time, so talk to us to confirm what you qualify for right now.
NATIONAL SCHEME
The Australian Government 5% Deposit Scheme
The Australian Government 5% Deposit Scheme (formerly the Home Guarantee Scheme) can help you buy your first home sooner. From 1 October 2025 the Scheme expanded, with no income caps, no waitlists and no Lenders Mortgage Insurance.
- Low deposit - a minimum 5% for first home buyers (2% for eligible single parents or guardians)
- No income caps - your income does not restrict your access
- No Lenders Mortgage Insurance - reducing your upfront costs
- Wide choice of homes - houses, townhouses, apartments, house and land, off-the-plan or building on vacant land, at or below location price caps
- Government-backed - a guarantee is provided to your lender
- Unlimited spots - apply when you are ready, no queue
To be eligible you generally need to be an Australian citizen or permanent resident aged 18 or over, have a 5% deposit, not have owned property in Australia in the last 10 years, buy at or below your location’s price cap, and live in the home as an owner-occupier. You must also meet your lender’s credit policy. We will check your eligibility and match you to a participating lender.
Borrowing from the bank of mum and dad
With affordability getting tricky for some, many first home buyers reach out to family for financial help to increase their borrowing power. Partnering with family can reduce the burden and may mean a better quality property, but it is not a move to make lightly. Make sure each party understands their financial and legal obligations, seek legal advice, and talk through what would happen if circumstances change. We recommend speaking to a financial planner and lawyer before going ahead.
Rent out your first home
There is no rule that says you have to live in your first property. Many first home buyers are rent-investing – renting where they want to live and buying an investment property in a more affordable location. As with any investment, the key is to choose on financial merit, not emotion. Consider whether you are after capital growth or rental yield, and seek appropriate legal and financial advice so you understand how it affects your finances and tax.
Ready to buy your first home?
Talk to Ezy Loans for free, obligation-free advice on first home buyer loans, grants and the schemes you qualify for. We compare dozens of lenders, do the paperwork, and guide you all the way to settlement.
Written by Amrinder Singh – Mortgage & Finance Broker, Ezy Loans Australia. Credit Representative 505232, authorised under Australian Credit Licence 377294 (Mortgage Australia Group Pty Ltd).
This guide provides general information only and does not take into account your objectives, financial situation or needs. It is not financial, tax, credit or legal advice. Grant, scheme and stamp duty rules change and vary by state and circumstance, so confirm current details before you apply. All loans are subject to lender approval and eligibility criteria.
*No obligations. Just an honest total cost comparison before you consolidate anything.
Ezy Loans Australia is a Perth-based mortgage and finance brokerage helping first home buyers, investors and refinancers across Australia secure the right loan with confidence.
Contact Info:
- 905 Hay St, Perth WA 6000
- amrinder@ezyloansaustralia.com.au
- 0432 066 362