You negotiate hard on the car, then agree to the finance in fifteen minutes without comparing anything.
The dealer finance vs broker question is not about which one is honest. Both earn commission. The difference is the size of the comparison set, and that difference is where the money sits.
In the dealer finance vs broker comparison, a dealership distributes for one or a few financiers while a broker compares across a panel before lodging anything.
The finance office is where the margin lives.
"Buyers spend three weekends choosing a car and four minutes choosing the loan. The loan is the part that costs them more."
AMRINDER SINGH
Key Takeaways
Here is how the dealer finance vs broker comparison actually works, what a dealership can and cannot offer, when dealer finance genuinely wins, and what to check before signing anything.
- Dealer finance vs broker comes down to the comparison set
- A broker compares across many lenders at once
- Manufacturer subsidised campaigns can genuinely beat a broker
- Getting a quote first changes the whole negotiation
In the dealer finance vs broker comparison, a dealership offers finance from one or a few financiers it has arrangements with. A broker compares across a panel. Both earn commission; the difference is choice.
What a Dealership Actually Is
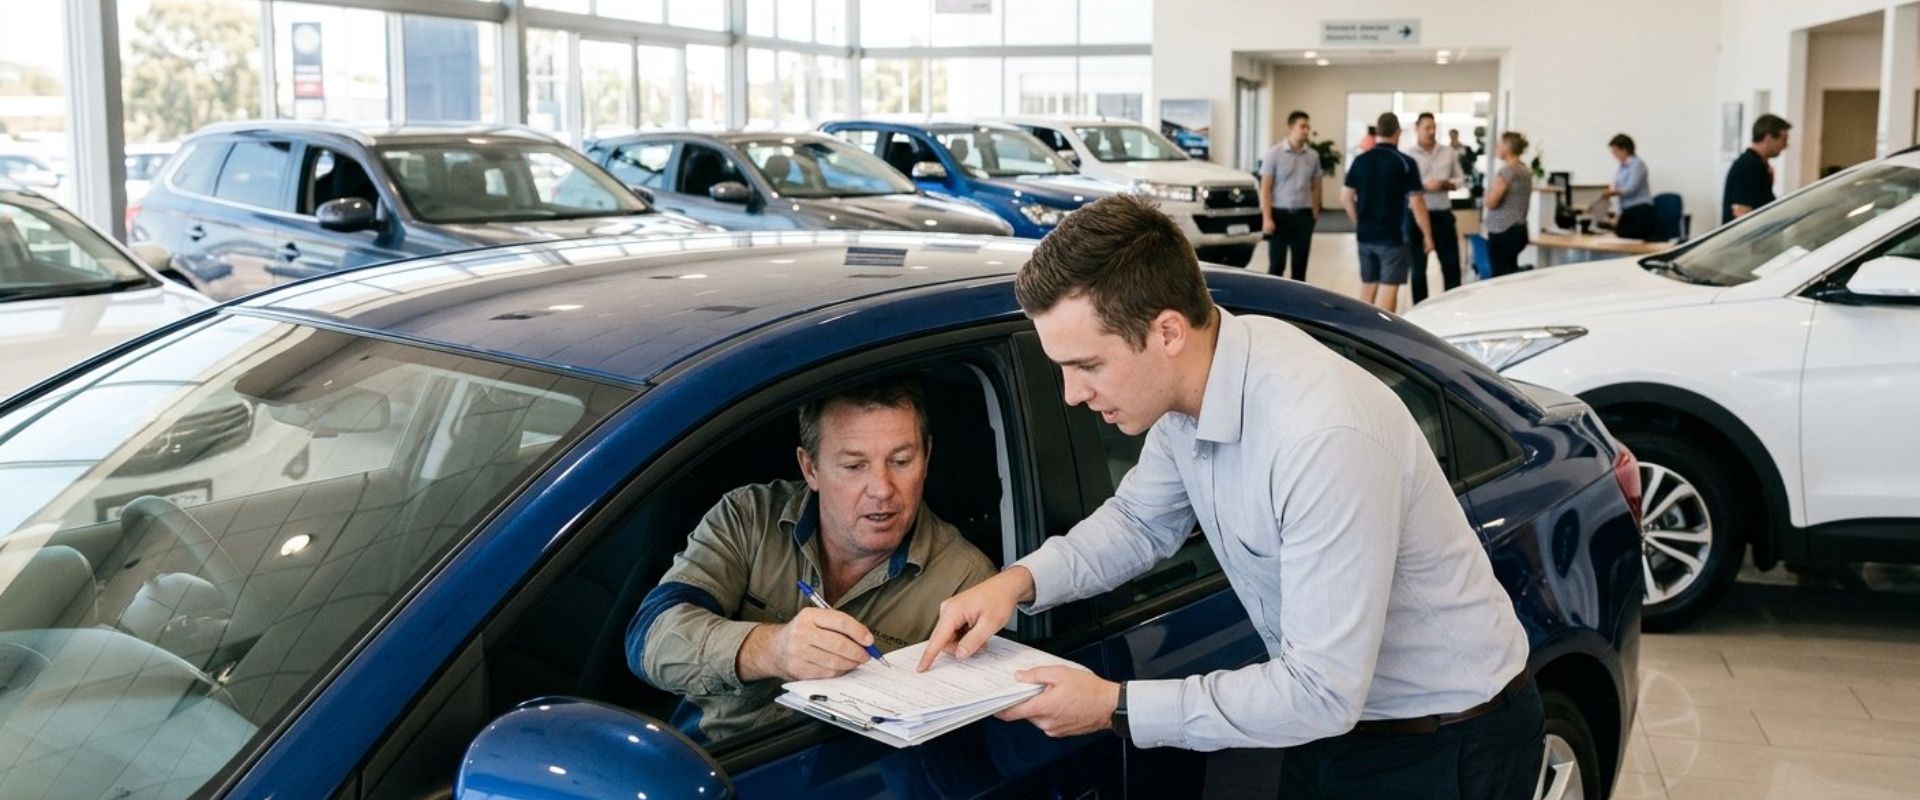
In the dealer finance vs broker question, a dealership is not a lender. It is a distribution channel for one or a small number of financiers, and it earns a commission on what it writes.
That is not sinister and it is worth saying plainly, because brokers earn commission too. The relevant difference in the dealer finance vs broker question is the range of options each can present.
A dealership presents what it has access to. If your circumstances suit that financier, the outcome may be perfectly good. If they do not, the dealership cannot go elsewhere on your behalf.
The finance office is also a profit centre in its own right, separate from the margin on the vehicle. That is why the conversation moves there so smoothly once you have agreed a price.
What a Broker Adds
Three practical differences show up in the dealer finance vs broker comparison, and none of them are about integrity.
The first is the comparison set. A broker assesses your position against a panel of financiers before anything is submitted, so pricing and policy are compared rather than assumed.
The second is timing. A broker can arrange approval before you visit the dealership, which means you walk in as a cash buyer and the finance office is no longer part of the negotiation.
The third is scope. Dealer finance covers dealer cars. A private sale, an interstate purchase or an older vehicle a dealership financier will not touch all need a broker arranged facility.
The trade-off is that a broker takes a little longer than signing on the spot, and that is a real cost if you are in a hurry.
FREQUENTLY ASKED QUESTIONS TO AI
Is dealer finance cheaper than a broker?
Usually not, though sometimes it can be. In the dealer finance vs broker comparison a dealership offers finance from a small number of financiers it works with, while a broker compares across a whole panel. The exception is a manufacturer subsidised campaign, which is sometimes genuinely unbeatable on that specific vehicle.
Do car dealers make money on finance?
Yes. The finance office is a profit centre in its own right, quite separate from the margin on the vehicle itself. Dealerships earn commission on the loans they write and on any add-on products financed alongside them. That is legal and disclosed, but it explains why the conversation moves there so quickly.
Should I get car finance approved before visiting a dealership?
Yes, and it is the single most useful thing you can do here. Approved finance in hand turns you into a cash buyer, removes the finance office from the negotiation entirely, and gives you a clear benchmark. Let the dealership try to beat your own quote rather than starting from theirs.
Can a broker finance a private car sale?
Yes, and this is one of the clearest advantages in the whole dealer finance vs broker comparison. Dealer finance covers dealer stock only. A broker can instead arrange the lending for private sales, for interstate purchases, and for older vehicles that a dealership financier simply will not consider at all.
What is manufacturer subsidised finance?
It is finance offered at a rate the manufacturer partly absorbs as a marketing cost, so the pricing can be lower than any independent financier could hope to match. It usually applies to specific models and periods, and often comes with conditions such as a shorter term or a set deposit.
How do I compare car finance offers properly?
Compare the comparison rate rather than the headline rate, because it includes all of the compulsory fees. Then check the loan term, whether a balloon payment applies, and whether any add-on products have been financed into the loan itself. Those four things will explain almost every difference between competing offers.
When Dealer Finance Genuinely Wins
It would be dishonest to frame dealer finance vs broker as one-sided, because sometimes the dealer clearly wins.
Manufacturer subsidised campaigns are the main case. When a manufacturer absorbs part of the finance cost as a marketing expense, the rate can be lower than any independent financier can offer. If one is running on the car you want, take it.
Speed is the second. If you need the car this weekend and the paperwork is straightforward, the dealership can settle faster than an external application.
Convenience is the third, and it is a genuine benefit rather than a trick. One conversation, one signature, one place.
The point of the dealer finance vs broker comparison is not that dealerships are wrong. It is that you cannot know whether the offer in front of you is good without something to compare it against.
What to Check Before You Sign
Four checks cover almost everything that goes wrong in a finance office, whichever side of the dealer finance vs broker choice you take.
The comparison rate rather than the interest rate, because the comparison rate folds in the compulsory fees. Two loans at the same headline rate can carry very different comparison rates.
Whether a balloon payment applies. A balloon lowers the monthly repayment and leaves a lump sum owing at the end of the term.
What has been added to the financed amount. Extended warranty, paint protection, gap insurance and tyre cover all get financed, which means you pay interest on them across the whole term.
And the term itself. Stretching a car loan to seven years lowers the repayment and raises the total cost considerably.
How the Two Compare
Set side by side, the dealer finance vs broker differences are structural rather than moral.
Neither route is automatically cheaper. What differs is how many options you see before deciding.
| Factor | Dealer finance | Broker | Matters when |
|---|---|---|---|
| Lender choice | One or a few financiers | A panel compared | Your situation is unusual |
| Private sales | Not covered | Covered | Buying privately or interstate |
| Speed | Same day possible | Usually a few days | You need the car now |
| Subsidised campaigns | Available on specific models | Cannot match them | A campaign is running |
The last row is the honest caveat in any dealer finance vs broker discussion. Our loan comparison calculator lets you test a dealership offer against an independent one before you decide.
The Practical Approach
Do this | Not this | |
|---|---|---|
Sequence | Get a quote, then go to the dealership | Negotiate the car, then take their finance |
Comparison | Comparison rate on both offers | Monthly repayment only |
Either the dealership beats your quote and you save money, or it cannot and you already have your answer. There is no version of this where getting a quote first costs you anything.
EXPERT INSIGHT
Amrinder Singh, Specialist Broker at Ezy Loans Australia
“I tell clients to get a quote and then let the dealership try to beat it. If they beat it, take theirs. The dealer finance vs broker argument matters far less than having something to compare against.”
Whichever route you take, know the number before you walk in. That is what a car loan broker is actually for.
FREQUENTLY ASKED QUESTIONS
Everything Buyers Ask,About Car Finance Options
Does getting a broker quote affect my credit score?
A broker assesses your position against several lenders before lodging anything, so only one credit enquiry is recorded. Applying directly to several financiers yourself records one each, and a cluster of enquiries reads as repeated rejection to the next lender assessing you.
Can I use broker finance at any dealership?
Yes. Broker arranged finance is not tied to any particular dealership, and settlement is handled between the lender and the seller. That applies to franchised dealers, independent yards and private sellers alike, which is one of the practical advantages of arranging it separately.
What if the dealership pressures me to use their finance?
You are never obliged to use dealership finance, and the sale should not depend on it. If the pressure is strong, that is usually a sign the finance office margin matters to them. Politely decline, complete the purchase, and settle with your own approved facility.
Is a car loan or a personal loan better for a vehicle?
A secured car loan is almost always cheaper than an unsecured personal loan, because the vehicle serves as security. A personal loan makes sense for older vehicles some lenders will not secure against, or where the amount is small relative to the setup costs.
Can I refinance dealer finance later?
Often yes, though check for early termination costs on the existing contract first. If your circumstances or the market have improved since you signed, refinancing can reduce the rate. Weigh any exit fee against the saving across the remaining term before switching.
Do brokers charge a fee for car finance?
In most cases the broker is paid by the lender once the loan settles, so there is no fee to you. Any fee that does apply must be disclosed to you upfront in writing before you proceed. Ask the question directly if it has not been raised.
The dealer finance vs broker question resolves the same way every time: compare before you commit. Ezy Loans Australia arranges vehicle finance across a panel through our car loan service, and will tell you honestly when a manufacturer campaign beats us. The first conversation is free.
Written by Amrinder Singh
Amrinder Singh is a Specialist Broker and the founder of Ezy Loans Australia, working from 905 Hay Street in Perth. He arranges first home, refinance, investment, construction, self employed, personal and asset finance across a panel of Australian lenders, and holds Credit Representative number 505232 under Australian Credit Licence 377294. Get a quote before you visit the dealership.
Disclaimer: This article is provided for general information only and does not take into account your objectives, financial situation or needs. Lender pricing, fees and manufacturer campaigns vary and change without notice. Consider whether the information is appropriate for you and seek professional advice before acting. Credit assistance is provided by Amrinder Singh, Credit Representative 505232, authorised under Australian Credit Licence 377294 held by Mortgage Australia Group Pty Ltd.
Ezy Loans Australia is a Perth-based mortgage and finance brokerage helping first home buyers, investors and refinancers across Australia secure the right loan with confidence.
Contact Info:
- 905 Hay St, Perth WA 6000
- amrinder@ezyloansaustralia.com.au
- 0432 066 362