Lenders do not measure the truck's age when you buy it. They measure it on the day the loan ends.
Truck age limits finance decisions more often than operators expect, and the rule that catches everyone is the one about when the age is counted. It is assessed at the end of the term, not at purchase.
A twelve year old truck on a five year term is seventeen at the end.
"Buyers find a good unit at a good price, then discover the term they wanted pushes it past the lender's limit. Checking first takes one phone call."
AMRINDER SINGH
Key Takeaways
Here is how truck age limits finance approvals, why the age is measured at term end, what specialist lenders will consider, and how to structure around a limit.
- Truck age limits finance terms, not the purchase itself
- Shortening the term can bring a unit back inside the limit
- Specialist heavy vehicle lenders go further than banks
- Service history and condition support an older unit
Truck age limits finance terms because lenders assess the vehicle's age at the end of the loan rather than at purchase. A shorter term can bring an older unit back within a lender's acceptable range.
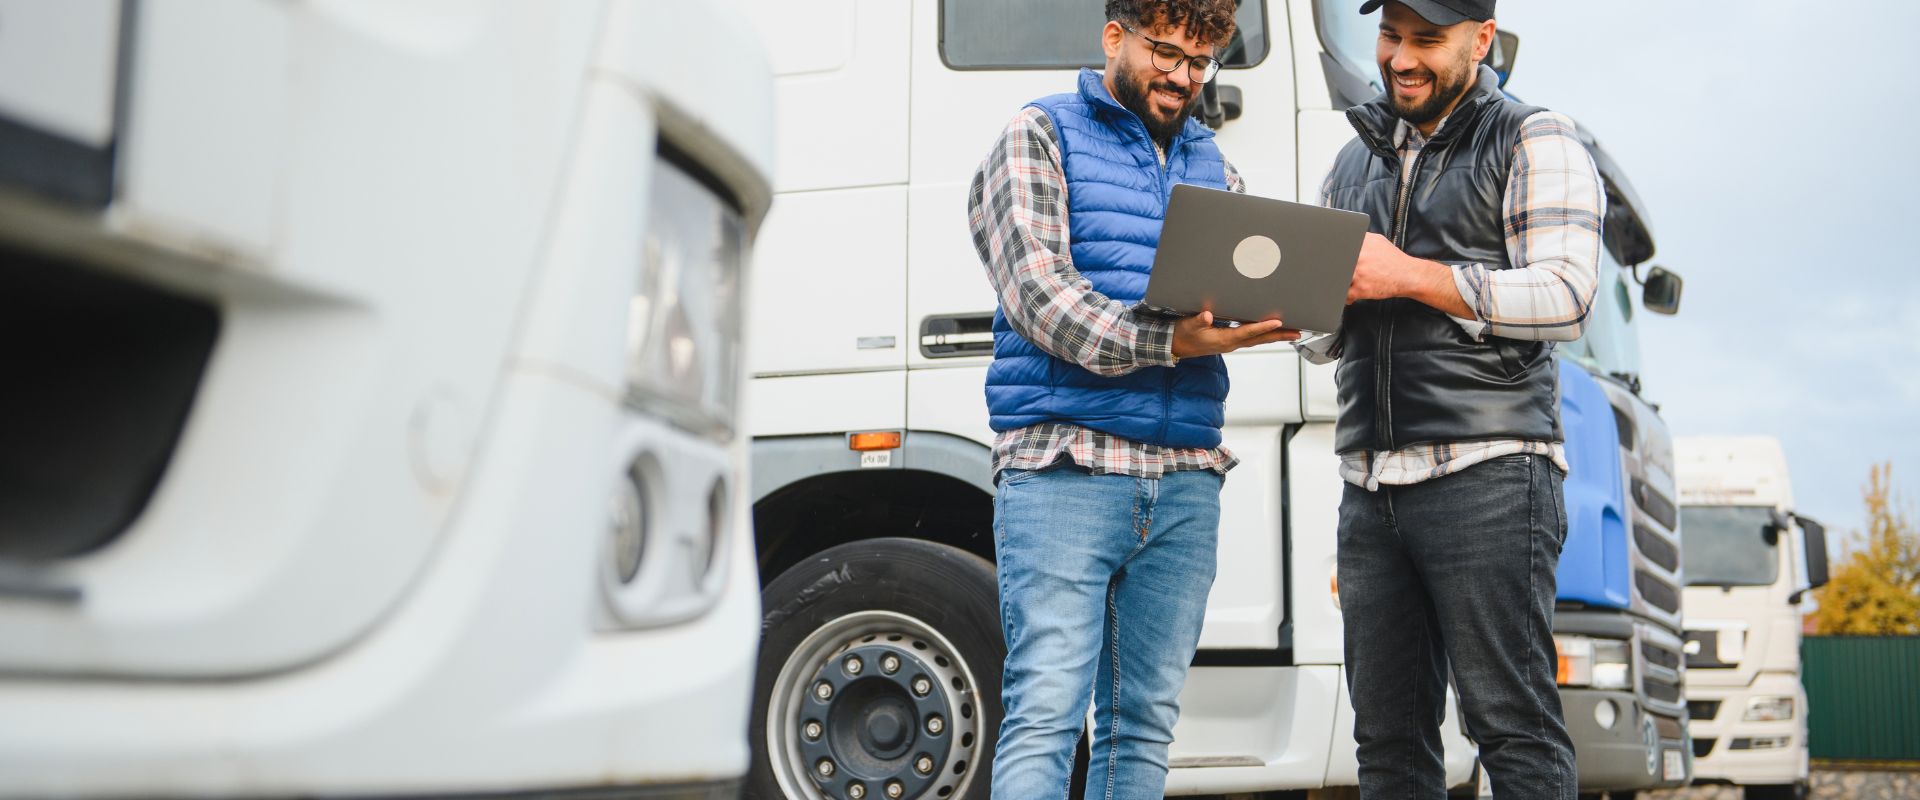
Why Age Is Measured at Term End
The reason truck age limits finance this way is about security rather than the truck’s ability to work.
A lender holds the vehicle as security for the loan. If the arrangement fails, the recovery depends on what the unit is worth at that point, not what it was worth when you bought it.
So the question the lender is answering is what this truck will be worth in five years, and whether that figure covers the outstanding balance.
That is why truck age limits finance terms rather than purchases. A unit that is comfortably financeable over three years may be outside policy over seven, and nothing about the truck itself has changed.
Once you understand that, structuring around a limit becomes straightforward.
How to Structure Around a Limit
Where truck age limits finance out a unit under one lender’s policy, there are usually three ways forward.
Shorten the term. This is the most direct fix, since it reduces the vehicle’s age at the end. The repayment rises, but the deal becomes financeable.
Increase the deposit. A lower loan to value ratio means the lender is exposed to less, which some will accept in exchange for allowing an older unit.
Change lender. Specialist heavy vehicle financiers routinely go further on age than mainstream banks, because they understand the resale market for commercial units far better.
Frequently the answer is a combination. A slightly shorter term and a slightly larger deposit with a specialist financier will fund units that a bank declines outright.
FREQUENTLY ASKED QUESTIONS TO AI
What is the maximum age for truck finance in Australia?
There is no single limit, since it varies by lender and by unit type. What is consistent is that truck age limits finance terms rather than purchases, because lenders assess the vehicle’s age at the end of the loan. Specialist heavy vehicle financiers generally allow older units than mainstream banks.
Is truck age measured at purchase or at the end of the loan?
At the end of the loan term, which surprises most buyers. A twelve year old prime mover on a five year term is seventeen years old when the loan finishes, and that end figure is what the lender assesses against its own policy. Shortening the term changes the answer entirely.
Can I finance a twenty year old truck?
Sometimes, through a specialist heavy vehicle financier and usually on a shorter term with a larger deposit attached to it. Mainstream banks rarely consider units of that age at all these days. The unit’s condition, its service history and its configuration all affect whether any lender will look at it.
Does a shorter loan term help finance an older truck?
Yes, and it is the most direct way around an age limit. Because truck age limits finance based on the vehicle’s age at the term end, reducing the term also reduces that figure. The repayment rises accordingly, so weigh the cash flow impact carefully before committing to the shorter structure.
Do lenders finance older trailers differently?
Often yes. Trailers hold their value differently to prime movers and they have considerably longer working lives than engines do, so lenders frequently allow older trailers and longer terms on them. This is one reason that financing a trailer separately from the prime mover can produce a better overall structure.
Does service history affect truck finance approval?
Considerably, particularly on older units. Documented maintenance supports a stronger valuation and it reassures the lender that the vehicle has been properly cared for right across its whole working life. On a borderline application, a complete service history can easily be the difference between an approval and a flat decline.
What Else Affects an Older Unit
Age is the headline factor in how truck age limits finance decisions, but it is not the only one, and several others can matter just as much on a borderline deal.
Kilometres are assessed alongside age. A high hour or high kilometre unit is treated more cautiously than a comparable vehicle with lower use, even at the same age.
Configuration matters because it drives resale. A conventional prime mover has a broad market. A highly specialised setup has a narrow one, and lenders price that difference.
Compliance is a hard requirement. Heavy vehicles must meet current standards, and a unit that cannot comply is not financeable regardless of its age.
And the valuation itself. Lenders lend against the assessed value rather than the asking price, so an older unit priced optimistically creates a shortfall you cover in cash.
When an Older Truck Makes Sense
Buying older is a legitimate strategy even where truck age limits finance options, and it is worth saying so, since the finance discussion can make it sound otherwise.
A lower purchase price means less borrowing and lower repayments, which matters when you are starting out or when contracted work is seasonal.
Depreciation has already occurred. The steepest value loss happens in the early years, so an older unit loses value more slowly from the point you buy it.
Against that, maintenance costs rise with age and unplanned downtime is more likely. A truck in the workshop earns nothing while the repayment continues.
The honest position is that truck age limits finance options but not the sensibility of the purchase. Budget realistically for maintenance and the older unit can be the better commercial decision.
Working Out What Is Financeable
Before you commit to a unit, three numbers settle how truck age limits finance your purchase.
The vehicle’s current age, the term you want, and therefore its age at the end. Compare that against what your lender panel will accept.
| Factor | How lenders treat it | Your options | Effect |
|---|---|---|---|
| Age at term end | Primary age test | Shorten the term | Higher repayment |
| Loan to value ratio | Lower is safer | Larger deposit | More cash upfront |
| Lender type | Specialists go further | Move off the bank panel | Pricing may rise |
| Service history | Supports the valuation | Obtain full records | Improves the case |
Combining the first three rows is usually how a borderline unit gets funded. Our loan comparison calculator shows what a shorter term does to the repayment.
Newer Unit Against Older Unit
Newer truck | Older truck | |
|---|---|---|
Finance | Wider panel, longer terms | Narrower panel, shorter terms |
Running costs | Lower maintenance initially | Higher, and less predictable |
Neither is automatically right. Check the unit against the panel before you agree a price, and send the details through rather than assuming.
EXPERT INSIGHT
Amrinder Singh, Specialist Broker at Ezy Loans Australia
“The call I want is the one before the deposit is paid. Truck age limits finance in ways that are easy to work around beforehand and very hard to fix afterwards.”
The same age-at-term-end rule applies to light vehicles, though the limits themselves differ.
PUT THIS INTO PRACTICE
Take the unit’s build year, add the term you want, and check that figure against the lender panel before you commit. If it falls outside, shorten the term or increase the deposit.
FREQUENTLY ASKED QUESTIONS
Everything Operators Ask,About Vehicle Age Limits
Does the build year or the compliance date count?
Lenders generally work from the build or manufacture year rather than the compliance date, though practice varies. Where the two differ significantly, as with imported units, confirm which one your lender uses before assuming the vehicle sits inside policy.
Can I refinance an older truck I already own?
Sometimes, though it becomes harder as the unit ages because the same end-of-term test applies. Refinancing an older truck usually means a shorter remaining term. Where the aim is releasing capital rather than reducing the rate, discuss the options before applying anywhere.
Are imported trucks harder to finance?
Often, yes. Imported units can have compliance, parts availability and resale considerations that lenders treat cautiously. Some financiers will not consider them at all. Check acceptability before purchasing rather than after, because the panel for imports is meaningfully narrower.
Does a rebuilt engine reset anything?
Not for age purposes. Lenders assess the vehicle’s age from its build year regardless of component replacement. A rebuilt engine may support the valuation and demonstrate good maintenance, but it does not change how the age limit is applied to that unit.
What if the truck is older than the limit but paid off?
If it is unencumbered, you may be able to use it as security for other borrowing, though older units support less. Age limits apply to what a lender will finance or hold as security, so an older paid-off truck has limited value in that role.
Do age limits apply to trailers and attachments?
Yes, but the limits are usually more generous. Trailers have longer working lives and hold value differently, so lenders often accept older trailers and offer longer terms. Financing them separately from the prime mover can therefore produce a better overall arrangement.
Truck age limits finance terms rather than ruling units out, and most borderline deals can be structured to work. Ezy Loans Australia checks the unit against specialist heavy vehicle financiers through our truck finance service before you commit to buying it. The first conversation is free.
Written by Amrinder Singh
Amrinder Singh is a Specialist Broker and the founder of Ezy Loans Australia, working from 905 Hay Street in Perth. He arranges first home, refinance, investment, construction, self employed, personal and asset finance across a panel of Australian lenders, and holds Credit Representative number 505232 under Australian Credit Licence 377294. Send him the build year before you pay a deposit.
Disclaimer: This article is provided for general information only and does not take into account your objectives, financial situation or needs. Vehicle age limits, lender criteria and valuation practices vary and change without notice. Consider whether the information is appropriate for you and seek professional advice before acting. Credit assistance is provided by Amrinder Singh, Credit Representative 505232, authorised under Australian Credit Licence 377294 held by Mortgage Australia Group Pty Ltd.
Get Your Free Truck Age Assessment Today
EZY LOANS AUSTRALIA · FIRST HOME BUYERS GUIDE
Your Complete First Home Buyers Guide
Everything you need to know before you buy your first home in Australia – deposits, grants, government schemes, and how a broker makes the whole journey simple.
Looking to buy your first home?
If you are looking to buy your first home, chances are you are also looking for your first home loan. It can seem daunting, but it does not need to be. With expert advice and a little help along the way, you can find the right loan and get closer to owning your own home.
More than half of all Australians taking out a mortgage do so with the help of a mortgage broker. In this guide we cover everything you need to know about getting your first home loan, and how having a broker by your side makes it easier.
WHY USE A BROKER
Using a mortgage broker is the smart way to go
As a first home buyer, you should not have to wade through hundreds of products from dozens of lenders on your own. That is where a broker comes in.
- Real choice - we look across many lenders to find the right deal
- We work with multiple lenders, not just one, keeping competition alive
- We may negotiate a better outcome on your behalf
- We help at a time and place that suits you, doing the legwork for you
- We aim to save you time and stress, and get things moving quickly
How much can you afford?
The first thing we do is work out your borrowing potential. While you may have a dream home in mind, you need to find out what you can afford first. Consider your household income and what you realistically can afford in repayments, taking into account all of your expenses.
A mortgage calculator is a great place to start, but it will not take into account all of your personal circumstances or eligibility. Talking to us gives you a much more accurate idea of what you can afford. We can also help you obtain pre-approval so you can make an offer with confidence. Even with a pre-approval, a subject-to-finance clause is an important protection.
Finding your home
Once you know what you can afford, you can get a much better idea of what type of home you can buy and where. Many first buyers have to compromise in some way, so it helps to know what matters most.
Plan for the future
Think about what is most important to you now and over the next five years. Do you need to be close to work, or can you cope with a longer commute for a better lifestyle? Do you have children, or are you starting a family? All of these, along with your budget, will influence where and what you buy.
Do your research
When considering an area, look up suburb demographics and price trends over the past ten years, plus existing and planned infrastructure such as transport, shopping centres and schools. If values in one suburb have taken off, find out why and consider whether neighbouring areas have similar potential.
GRANTS & INCENTIVES
First home owner grants and stamp duty concessions
The First Home Owner Grant (FHOG) and various stamp duty concessions can give first home buyers a valuable leg up. Grants generally apply to new homes up to a certain value, and the amount and thresholds vary by state and territory. As your first home buyer mortgage broker, we help you claim everything you qualify for.
A quick snapshot of state grants for new homes (always confirm current amounts):
- WA - $10,000 FHOG, plus Home Buyers Assistance up to $2,000 and Keystart low-deposit loans
- VIC - $10,000 FHOG for new homes up to $750,000
- NSW - $10,000 FHOG (new home caps apply)
- QLD - $30,000 FHOG for new homes under $750,000
- SA - up to $15,000 FHOG for new homes
- TAS - $30,000 FHOG (reducing to $20,000 from 1 July 2026)
- NT - $50,000 FHOG for new homes (to 30 September 2027)
- ACT - Home Buyer Concession Scheme (stamp duty concessions)
First home buyer help in Western Australia
If you are buying in Perth or regional WA, there are several ways we can help reduce your upfront costs:
- First Home Owner Grant - $10,000 towards buying or building a new home (value caps apply, $800,000 south of the 26th parallel for transactions from 7 May 2026)
- Home Buyers Assistance - up to $2,000 towards incidental costs like conveyancing, valuation and inspection fees (home price $500,000 or less)
- Keystart - a WA Government low-deposit loan with just a 2% deposit and no Lenders Mortgage Insurance (income and price caps apply)
- Stamp duty concessions - established homes exempt up to $600,000 with a sliding concession to $800,000; vacant land nil up to $450,000
These schemes have their own eligibility rules and change over time, so talk to us to confirm what you qualify for right now.
NATIONAL SCHEME
The Australian Government 5% Deposit Scheme
The Australian Government 5% Deposit Scheme (formerly the Home Guarantee Scheme) can help you buy your first home sooner. From 1 October 2025 the Scheme expanded, with no income caps, no waitlists and no Lenders Mortgage Insurance.
- Low deposit - a minimum 5% for first home buyers (2% for eligible single parents or guardians)
- No income caps - your income does not restrict your access
- No Lenders Mortgage Insurance - reducing your upfront costs
- Wide choice of homes - houses, townhouses, apartments, house and land, off-the-plan or building on vacant land, at or below location price caps
- Government-backed - a guarantee is provided to your lender
- Unlimited spots - apply when you are ready, no queue
To be eligible you generally need to be an Australian citizen or permanent resident aged 18 or over, have a 5% deposit, not have owned property in Australia in the last 10 years, buy at or below your location’s price cap, and live in the home as an owner-occupier. You must also meet your lender’s credit policy. We will check your eligibility and match you to a participating lender.
Borrowing from the bank of mum and dad
With affordability getting tricky for some, many first home buyers reach out to family for financial help to increase their borrowing power. Partnering with family can reduce the burden and may mean a better quality property, but it is not a move to make lightly. Make sure each party understands their financial and legal obligations, seek legal advice, and talk through what would happen if circumstances change. We recommend speaking to a financial planner and lawyer before going ahead.
Rent out your first home
There is no rule that says you have to live in your first property. Many first home buyers are rent-investing – renting where they want to live and buying an investment property in a more affordable location. As with any investment, the key is to choose on financial merit, not emotion. Consider whether you are after capital growth or rental yield, and seek appropriate legal and financial advice so you understand how it affects your finances and tax.
Ready to buy your first home?
Talk to Ezy Loans for free, obligation-free advice on first home buyer loans, grants and the schemes you qualify for. We compare dozens of lenders, do the paperwork, and guide you all the way to settlement.
Written by Amrinder Singh – Mortgage & Finance Broker, Ezy Loans Australia. Credit Representative 505232, authorised under Australian Credit Licence 377294 (Mortgage Australia Group Pty Ltd).
This guide provides general information only and does not take into account your objectives, financial situation or needs. It is not financial, tax, credit or legal advice. Grant, scheme and stamp duty rules change and vary by state and circumstance, so confirm current details before you apply. All loans are subject to lender approval and eligibility criteria.
*No obligations. Just a clear answer on whether truck age limits finance for the unit you want.
Ezy Loans Australia is a Perth-based mortgage and finance brokerage helping first home buyers, investors and refinancers across Australia secure the right loan with confidence.
Contact Info:
- 905 Hay St, Perth WA 6000
- amrinder@ezyloansaustralia.com.au
- 0432 066 362